Health insurance is one of the most important safety nets you can have, but unless you are retiring, you can’t take your TRICARE coverage with you.
If you are leaving the military, health insurance should be one of the first things you address before the first day of your post-military life. Fortunately, your coverage doesn’t end the day you separate, but it will eventually expire.
In this guide, you will learn what happens to your health coverage after separation, which options are available to you and your family, and how to prepare for your transition with a pre-separation health insurance checklist.
What Happens to Your Health Insurance When You Leave the Military?
After you separate from the military, you have several health insurance options depending on your type of separation and eligibility status.
Transitional Assistance Management Program (TAMP): TAMP provides up to 180 days of premium-free TRICARE coverage to qualifying separating service members and their families.
Continued Health Care Benefit Program (CHCBP): CHCBP is a premium-based plan that provides 18 months of temporary coverage for service members and families who lose TRICARE eligibility upon separation, serving as a bridge to civilian health insurance coverage.
VA Health Care: VA health care benefits are available for eligible veterans based on active-duty service dates, type of discharge, income, and deployment locations.
The Health Insurance Marketplace: Often referred to as the ACA Marketplace, you can purchase health insurance here if you don’t qualify for TRICARE, VA health care, or private insurance through an employer.
Health Insurance Coverage Timeline After Separation
|
Program |
Length of Coverage |
Cost / Pricing (2026 Rates) |
Enrollment / Election Window |
|---|---|---|---|
|
Transitional Assistance Management Program (TAMP) |
180 days for eligible service members |
Premium-free. Deductibles, co-pays, or cost-shares may apply. |
Automatic upon qualifying discharge/separation. You have 90 days from start of TAMP to enroll in a TRICARE plan. |
|
Continued Health Care Benefit Program (CHCBP) |
18 months for separating members and families. Up to 36 months for unmarried former spouses. |
$2,103/quarter for an individual. $5,339/quarter for a family. |
Within 60 days of losing TRICARE eligibility or TAMP coverage. |
|
VA Healthcare |
Ongoing for eligible enrolled veterans. |
No copays for service-connected care; small copays may apply depending on disability rating, income, service, and exemptions. |
Can apply anytime. One-time dental care is limited to within 180 days of discharge. |
|
Health Insurance Marketplace (ACA) |
Coverage runs for the remaining plan year, and 12 months thereafter. Renewable annually during open enrollment. |
Varies based on household income and subsidy/tax credit eligibility. |
Generally, 60 days before or 60 days after the loss of prior coverage. Open enrollment opportunity beginning November 1 each year. |
Looking ahead to 2027: CHCBP quarterly premiums will increase to $2,280 for individual coverage and $5,741 for family coverage beginning January 1, 2027, according to TRICARE.
Which Health Insurance Option Is Right for You?
The best health insurance option after leaving the military depends on how you’re separating, whether you’re retiring, and who needs coverage.
If you have a spouse or children, you’ll also want to consider their health care needs. Qualifying for VA health care yourself doesn’t necessarily mean your family will be covered.
Here’s where to start based on your situation:
|
Your Situation |
Where to Start |
|---|---|
|
You’re involuntarily separating |
Check whether you qualify for 180 days of coverage through TAMP. |
|
You’re voluntarily separating and not retiring |
Compare CHCBP, employer-sponsored health insurance, and Marketplace plans. |
|
You’re separating with a spouse or children |
Look at family premiums, deductibles, and provider networks before choosing coverage. |
|
You’re starting a civilian job |
Ask your new employer when health benefits begin and whether there’s a waiting period. |
|
You qualify for VA health care |
Apply for VA benefits, but remember that your family may need separate coverage. |
|
You’re retiring from the military |
Review TRICARE retiree plans and the enrollment requirements that apply to you. |
You don’t have to settle on the first option available. Compare what each plan covers, what you’ll pay out of pocket, and whether your doctors are in the network.
Most importantly, find out when your current coverage ends. You don’t want to discover a gap in health insurance after you or someone in your family needs medical care.
TAMP: Who Qualifies for 180 Days of Coverage?
Transitional Assistance Management Program (TAMP) is a short-term health care program that provides up to 180 days of coverage to service members and their families who qualify after separation from the military.
TAMP bridges the gap in health insurance coverage until you can find and obtain coverage through a new employer, purchase an individual health care plan, or enroll in health care through the Department of Veterans Affairs (VA).
Who Qualifies for TAMP?
You and your family may be covered under TAMP if you are:
- Involuntarily separating from active duty under honorable conditions
- A National Guard or Reserve member separating from a period of active duty that was more than 30 consecutive days in support of a contingency operation
- Separating from active-duty following involuntary retention (stop-loss) in support of a contingency operation
- Separating from active-duty following a voluntary agreement to stay on active duty for less than one year in support of a contingency operation
- Separating from active duty with an agreement to become a member of the Selected Reserve of the Ready Reserve
- Separating from active duty due to a sole survivorship discharge
What Does TAMP Cover?
When you become eligible for TAMP, you and your family are automatically covered under TRICARE Select, and receive all the medical benefits as active-duty family members, including coverage subject to deductibles, cost-shares, and copayments.
VA Health Care After Military Separation
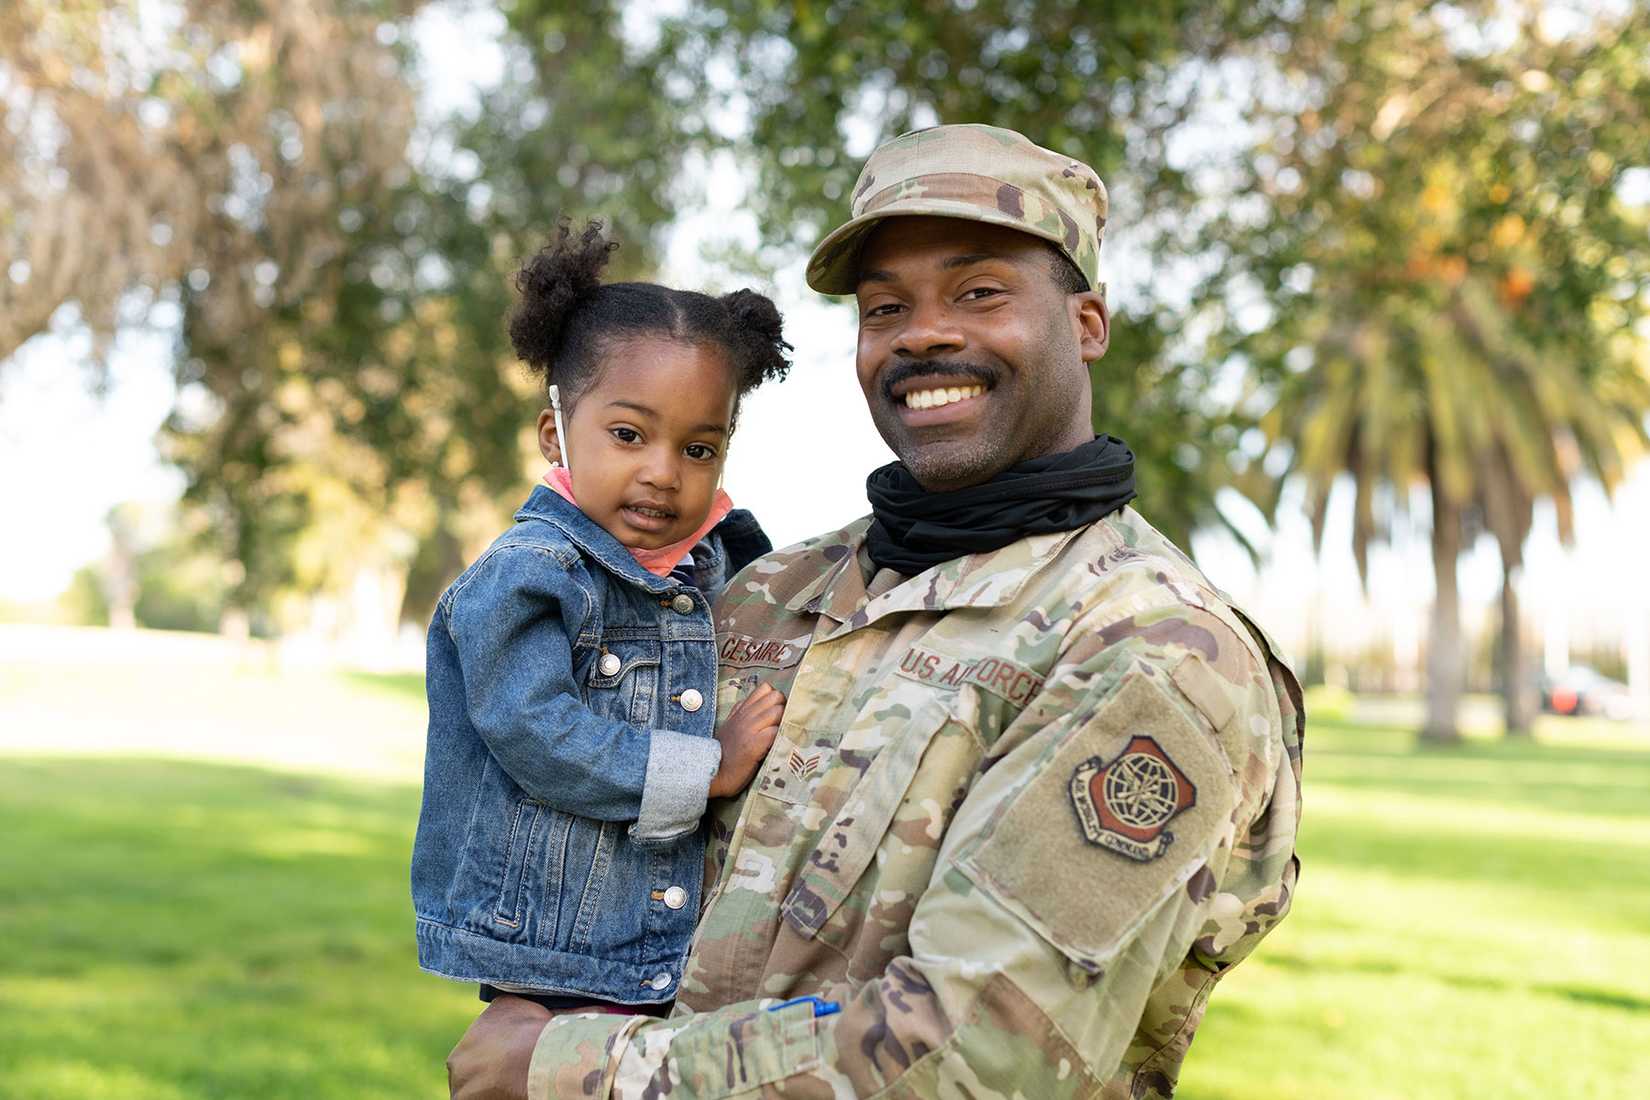
Senior Airman Jerry Cesaire, a passenger terminal agent with the 60th Aerial Port Squadron, poses with his daughter at Travis Air Force Base, California. While eligible veterans may receive VA health care after military separation, coverage does not automatically extend to spouses and children. Some family members may qualify for additional benefits through programs such as CHAMPVA.
Another option for health care after you leave the military is through the Department of Veterans Affairs (VA). The VA operates more than 1,300 healthcare facilities across the United States, including 170 major VA medical centers, and nearly 1,200 outpatient sites that deliver primary care, mental health counseling, and routine specialty care in your community.
You are covered for regular checkups with your primary care provider, as well as specialist care such as cardiology services, and access to programs like home health care and elder care.
Many veterans who served on active duty may qualify for VA health care based on service history, disability status, and income. However, family members are not automatically eligible for general VA health care. They may qualify through special VA health programs for family and caregivers.
Who Is Eligible for VA Health Care?
According to the VA, you may be eligible if you served on active duty, and did not receive a dishonorable discharge, and either enlisted after September 7, 1980, or were commissioned as an officer after October 16, 1981, and completed at least 24 continuous months of service.
Even if you do not meet the minimum service time requirements or have a low income, you may still qualify for VA health care if any of these are true:
- You were discharged for a disability that was caused—or made worse—by your active-duty service.
- You were discharged for a hardship or “early out.”
- You served prior to September 7, 1980.
Check with the VA to see if you qualify for enhanced eligibility status if you were exposed to toxins or other hazards while serving your country in the Vietnam War, Gulf War, Iraq, Afghanistan, or any other combat zone after 9/11.
Does VA Health Care Cover Your Spouse and Children?
One thing to keep in mind when transitioning out of the military is that qualifying for VA health care doesn’t automatically provide coverage for your spouse or children.
However, some families may qualify for the Civilian Health and Medical Program of the Department of Veterans Affairs (CHAMPVA).
CHAMPVA helps cover certain medical expenses for eligible spouses and dependent children of veterans who have been rated permanently and totally disabled due to a service-connected disability. Certain surviving family members may also qualify.
There’s an important catch: If your family members are eligible for TRICARE, they generally cannot receive CHAMPVA benefits.
If you’re leaving the military with a family, check whether your dependents qualify for CHAMPVA before purchasing separate insurance. Otherwise, you may need to consider an employer-sponsored plan, Marketplace coverage, or another option to make sure everyone is covered.
You can learn more about eligibility and how to apply through the VA’s CHAMPVA program.
CHCBP vs. Marketplace vs. Employer Health Insurance
After leaving the military, many veterans and their families must choose between CHCBP, an ACA Marketplace plan, or employer-sponsored health insurance. Each option differs in cost, coverage length, provider flexibility, and financial assistance, making it important to compare your choices before your TRICARE eligibility ends.
Comparing Costs, Coverage and Enrollment Deadlines
|
Attribute |
CHCBP |
ACA Marketplace (Healthcare.gov) |
Employer-Sponsored Coverage |
|---|---|---|---|
|
Duration |
Temporary: 18 to 36 months depending on qualifying event. |
Ongoing; renewed annually during Open Enrollment or Special Enrollment Period (SEP). |
Active as long as you maintain eligible employment status. |
|
Premiums |
Individual: $2,103/quarter Family: $5,339/quarter |
Individual: $0 to $600+/month Family: $0 to $1,500+/month (Varies widely by age and region) |
Plan-specific employee contribution. Individual: $139/month Family: $623/month Source: KFF 2026 national averages, employee share |
|
Subsidies and Financial Aid |
None. Must pay the full published quarterly premium. |
Available: Advance Premium Tax Credits (APTC) and Cost-Sharing Reductions (CSR), depending on household income. |
Built-in: Employer pays the majority of the premium; pre-tax payroll deductions reduce taxable income. |
|
Out-of-Pocket Costs |
TRICARE deductibles and copays apply. Catastrophic caps: $1,324 per family for active-duty, $4,635 per family for a retired sponsor. |
Deductibles and copays depend on plan tier (Bronze, Silver, Gold, Platinum). Catastrophic caps: $10,600 for individuals and $21,200 per family. |
Generally moderate to low deductibles/copays. Often includes Health Savings Account (HSA) or Flexible Spending Account (FSA) options. |
|
Annual Deductible |
Active duty, E-1 – E-4: Individual: $66 Family: $132 Active duty, E-5+: Individual: $198 Family: $397 |
The average annual deductible is $3,786 per person. Range is $0 for Gold plans and $7,476 for Bronze plans. Source: KFF |
Standard PPO: $1,446 HDHP/HSA: $2,912 Source: KFF |
|
Copays / Cost-Share |
Primary Care: $19 per visit in network Specialist: $33 per visit in network Urgent Care: $27 in network ER Visit: $52 in network |
Primary Care: $0 – $50 Specialist: $30 – $100+ Coinsurance: 10% – 40% after deductible Actual costs depend on plan and service. |
Primary Care: $15 – $30 Specialist: $30 – $50 Coinsurance: 10% – 20% after deductible Actual costs depend on plan and service. |
What Happens If You Miss Your Health Insurance Enrollment Deadline?
One mistake you don’t want to make when leaving the military is assuming you can sign up for health insurance whenever you’re ready.
Different programs have different enrollment deadlines, and missing one could leave you and your family without coverage.
For example, if you qualify for the Continued Health Care Benefit Program (CHCBP), you must purchase coverage within 60 days of losing your TRICARE eligibility, including TAMP. Miss that window, and you could lose the opportunity to enroll in CHCBP.
The Health Insurance Marketplace has its own rules. Losing qualifying health coverage generally gives you a Special Enrollment Period, allowing you to enroll in a Marketplace plan within 60 days before or after your existing coverage ends. If you miss that opportunity, you may have to wait until the next Open Enrollment Period unless you qualify for another exception.
If you’re starting a civilian job, check with your employer about when your new benefits begin and how long you have to enroll.
My advice? Don’t wait until your last day in uniform to figure this out. Find out when your coverage ends, mark your enrollment deadlines, and start comparing options before you separate.
For more information, visit TRICARE’s CHCBP enrollment guide or HealthCare.gov.
What If You’re Retiring From the Military?
If you qualify for retirement, congratulations! When I retired, I knew that my family’s health insurance needs would be covered through TRICARE, and that my family and I would be covered for life.Here are health insurance options for retired service members:
- TRICARE Prime: A managed-care plan available in designated Prime Service Areas. There are lower out-of-pocket costs, but you must work through a Primary Care Manager (PCM) and referrals for specialty care.
- TRICARE Select: A fee-for-service plan that offers more freedom to choose a provider without referrals.
- TRICARE for Life (TFL): Once you turn 65 and sign up for Medicare Parts A and B, you are eligible for TFL. TRICARE then becomes a secondary insurance after Medicare pays its portion. I recently signed up for TFL, and the process was painless. You just sign up for Medicare through your Social Security portal, and you will be notified when it has processed.
Pro Tip: Don’t forget to get a new retiree ID card when you turn 65, it will show your transition to TRICARE for Life.
- TRICARE Retired Reserve: If you are an actively drilling member of the Guard or Reserves, and not yet 60 years of age, you may be eligible.
- Military Retiree Dental Care and Vision Insurance: Dental and vision insurance is offered to military retirees through the FEDVIP program. It is a voluntary program under which you pay a premium each month for each program you opt for.
A 90-Day Pre-Separation Health Insurance Checklist
When you are 90 days away from military separation, your focus should shift from general transition planning to securing post-military medical care and identifying coverage for your family.
90 to 60 Days Before Separation
- Complete Your Separation Health Physical Examination (SHPE)
- Schedule and complete your mandatory SHPE through your military treatment facility (MTF) to document all service-connected conditions for VA claim purposes.
- Gather Medical Records
- Download copies of your military medical, dental, and pharmacy records from MHS GENESIS Patient Portal or request physical copies from your base records department.
- Verify TRICARE Coverage End Date
- Confirm your official active-duty separation date to determine the exact end of your standard TRICARE coverage (11:59 p.m. your last active-duty service day).
- Check TAMP Eligibility
- Qualify if involuntarily separated, separating under certain voluntary programs, or returning from active-duty support for Reserve/National Guard.
-
Identify Your Day-After Separation Coverage Option:
- TAMP
- VA Healthcare
- TRICARE Retiree Coverage
- Employer Health Plan
- ACA Marketplace
60 to 30 Days Before Separation
- Project Post-Separation Household Income
- Calculate your expected post-military income (civilian salary, VA disability rating estimates, household earnings) to check eligibility for ACA Marketplace subsidies.
- Run Costs vs. Coverage Comparisons
- Compare your potential post-service options based on your budget, health care needs, and provider preferences:
- Employer Coverage: Review the benefits package and enrollment deadlines for your new civilian job.
- CHCBP (Continued Health Care Benefit Program): Evaluate if maintaining TRICARE providers via CHCBP is worth the high quarterly premium.
- ACA Marketplace: Preview plans and premium tax credits on Healthcare.gov.
- Request Continuity of Care Authorizations
- If you or a family member are undergoing specialized care or pregnancy, request treatment summary documentation from your providers to submit to your new insurer.
30 to 0 Days Before Separation
- Trigger Your Special Enrollment Period (SEP)
- Loss of TRICARE is a Qualifying Life Event (QLE). Use this status to apply for an ACA Marketplace plan or your employer’s plan up to 60 days before or 60 days after your separation date.
-
Submit Plan Enrollment
- If Choosing CHCBP: Complete and submit DD Form 2837 within 60 days of losing TRICARE/TAMP eligibility.
- If Choosing Employer/Marketplace: Complete enrollment and set your coverage start date to your official separation date to avoid coverage gaps.
- Set Up Initial Premium Payments
- CHCBP: Prepare to pay the first 90-day quarterly premium in advance upon submitting your application.
- Commercial Plans: Set up automatic monthly payments so coverage activates seamlessly on day 1 post-separation.
Bottom Line
Leaving the military doesn’t mean losing access to health care, but it does require planning. Whether you qualify for TAMP, VA health care, CHCBP, retiree TRICARE benefits, or an ACA Marketplace plan, understanding your options before separation can help you avoid costly coverage gaps. By starting your health insurance transition at least 90 days before separation, you can ensure continuous coverage for both yourself and your family during one of life’s biggest transitions.
FAQ
Q: Can I enroll in the Marketplace when TAMP ends?
Yes. The loss of TAMP coverage qualifies you for a Special Enrollment Period, allowing you to enroll in a Marketplace plan outside Open Enrollment.
Q: How long does TAMP last?
TAMP provides up to 180 days of premium-free TRICARE coverage for eligible members and their families.
Q: Is CHCBP worth it, or should I buy Marketplace insurance?
CHCBP may be worth it if you want to keep TRICARE-style coverage and providers. Marketplace plans are often more affordable if you qualify for subsidies.
Q: Do I need to enroll in CHCBP before my TRICARE coverage ends?
Yes. You must apply for CHCBP within 60 days of losing TRICARE eligibility or TAMP coverage to maintain eligibility for the program.
Q: Does VA health care cover my family after I separate?
Generally, no. VA health care primarily covers eligible veterans, though some family members may qualify for programs such as CHAMPVA
Q: Can I use VA health care and private insurance at the same time?
Yes. Many veterans use VA health care alongside employer-sponsored, Marketplace, Medicare, or other private health insurance to expand their coverage options and access to care.
Q: Does retirement TRICARE start automatically?
No. Retirees must enroll in the appropriate TRICARE plan and keep their DEERS information current. TRICARE For Life begins when you’re eligible for Medicare Part A and enrolled in Part B.
Q: What about retiree dental and vision coverage?
Retirees and eligible family members can purchase dental and vision insurance through the FEDVIP program.
Read the full article here
39 Comments
If AISC keeps dropping, this becomes investable for me.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
I like the balance sheet here—less leverage than peers.
Production mix shifting toward USA might help margins if metals stay firm.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
The cost guidance is better than expected. If they deliver, the stock could rerate.
Nice to see insider buying—usually a good signal in this space.
If AISC keeps dropping, this becomes investable for me.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
I like the balance sheet here—less leverage than peers.
I like the balance sheet here—less leverage than peers.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
Interesting update on Health Insurance After Military Separation: Your Options. Curious how the grades will trend next quarter.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
Interesting update on Health Insurance After Military Separation: Your Options. Curious how the grades will trend next quarter.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
Nice to see insider buying—usually a good signal in this space.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
Uranium names keep pushing higher—supply still tight into 2026.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
If AISC keeps dropping, this becomes investable for me.
Nice to see insider buying—usually a good signal in this space.
Good point. Watching costs and grades closely.
Good point. Watching costs and grades closely.
Uranium names keep pushing higher—supply still tight into 2026.
Nice to see insider buying—usually a good signal in this space.
Good point. Watching costs and grades closely.
Production mix shifting toward USA might help margins if metals stay firm.
Good point. Watching costs and grades closely.
I like the balance sheet here—less leverage than peers.
Good point. Watching costs and grades closely.